
An alternative to alternatives
Shedding the light on how our trading information is brought to light and the depth we have to go too in sourcing new ideas / what we like to call “outside of the box thinking.”
Reaching a wide variety of different asset classes from Forex, Commodities, Shares, Equities and Credit. Within each asset class, we break down the sectors we are most active in.
Our Strategies
30+
Markets Traded
5+
Asset Classes
Covering
POTAM, 8.3, 8.5 disclosures
Spanning
Emerging and Developed Markets
Spanning a variety of asset classes helps keep us varied in our approach to finding alpha.
We aim to capture the difference between bond spreads at their widest point from conversion prices generated by temporary imbalances and then crystallise profit once the factors that have caused these imbalances and mispricings dissipate. We are particularly active in the travel, leisure, and entertainment sectors where bond issuance is high.
Our approach is simple; we always try to ensure the delta is very balanced so that we have potential upside; the real work comes from our credit analysis to ensure stability throughout. We look at the full spectrum of the company, from the credit to the equity evaluation.

Forex
Developed & Emerging Currency Pairs
We typically start by looking at capital flight accounts, pairing with portfolio inflows and foreign holdings.
Being especially active in the EM and DM FX sectors we look at perceived sentiment by non-residents just as much as thematic themes to gauge interest in the marketplace.
Through heavily tracking CB’s selling and repo agreements, flows into local state funds such as OFZ bonds. We focus heavily on the corporate side, such as corporate hoarding rates and burn rates for cash piles to gauge FX volumes and demand.
Too see more on our analysis click below


Commodities
Energy, Metals, E&P, Super-majors, Futures
We split time across a wide range of commodities. Lately, our focus has been on both state and privately held oil firms.
State oil firms with USD-and EUR-issued bonds. We focus specifically on calculating relative borrowing costs for global firms issuing USD -and EUR-denominated bonds by looking at yields and price data in the secondary market.
The underlying assumption is that if a firm were to issue a bond on a given observation date, if would be issued at a yield that does not deviate much from the yield curve of the firm’s outstanding debt trading on that observation date. We come in and look for bigger spreads between the primary and secondary markets.
Too see more on our analysis click below
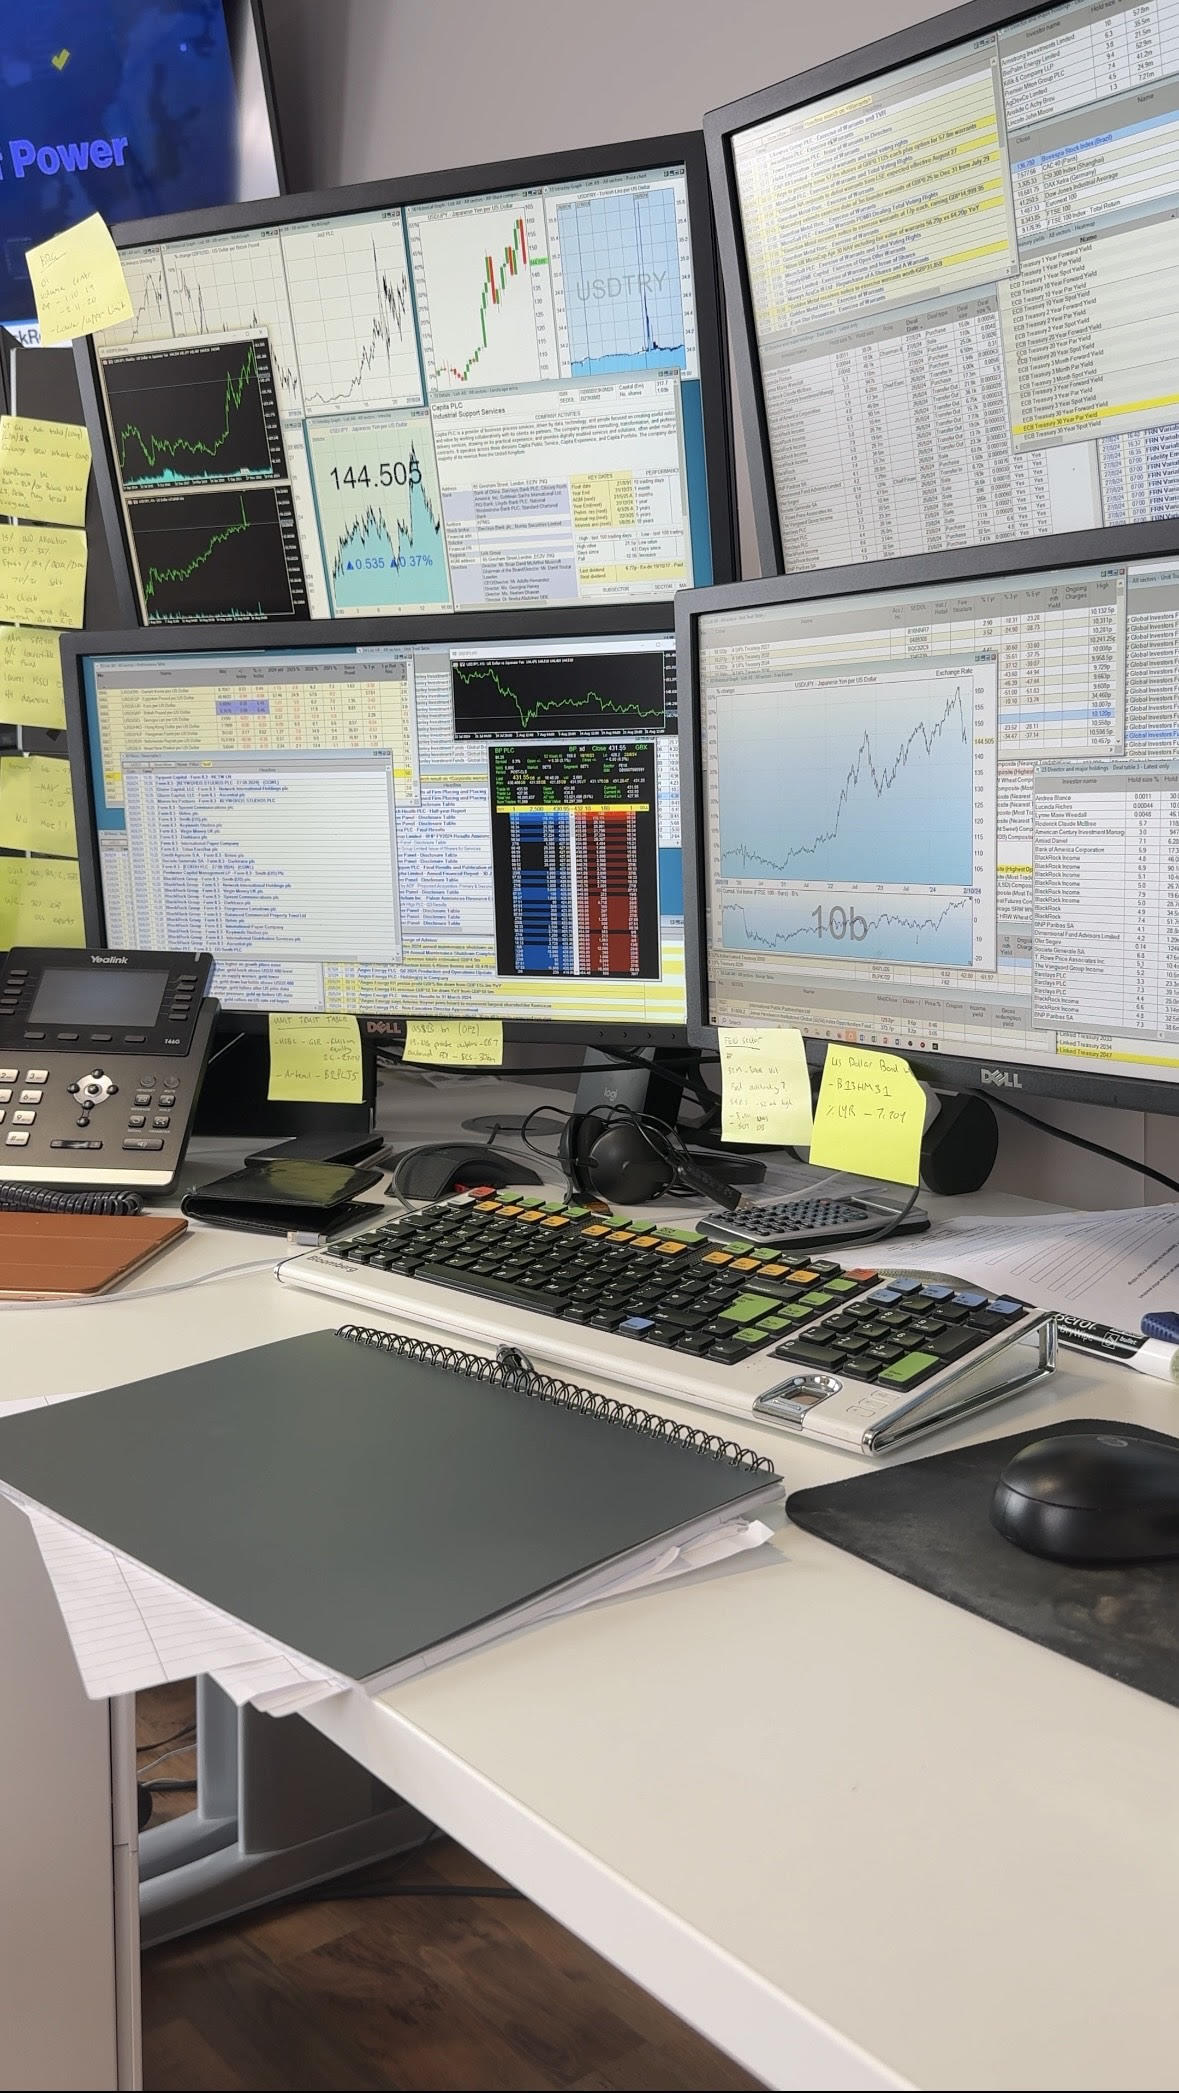
Stocks & shares
U.K., Eurozone, USA, Large Cap – AIM, IPO, Penny Stocks
Stocks make up a considerable allocation, both long and short.
Spanning the U.K., Eurozone, USA, LatAm, and Asia.
A good portion of our analysis and research comes from 8.3 and 8.5 disclosure forms, POTAM, etc. With heavy emphasis on credit, we typically incorporate our in-house convertible bond strategy that runs alongside the underlying equity.
Too see more on our analysis click below

Bonds & Credit
Convertible Bonds
We aim to capture the difference between convertible bond spreads at their widest point from conversion prices, generated by temporary imbalances, and then crystallise profit once the factors that have caused these imbalances and mispricing’s dissipate.
We are particularly active in the travel, leisure, and entertainment sectos, where bond issuance is high.
We also take an active trading approach to the underlying equity, cherrypicking our entries for the widest point from conversion to share price.
Too see more on our analysis click below